Futures & Market Research Glossary
Some of the most familiar futures terms are also the easiest to misunderstand. Trading volume counts contracts changing hands, while open interest measures contracts still outstanding. The two can move in different directions, and confusing them can lead to very different readings of market activity.
This glossary covers futures contracts, COT classifications, term structure, spreads, seasonality, volatility and statistical concepts used in financial research. Alongside the definitions, you'll find explanations of the mechanics involved and the circumstances in which particular measures become useful.
Contract specifications, reporting conventions and calculation methods can make a considerable difference. A trader category in one COT report, for instance, isn't automatically equivalent to a similar category in another. Understanding such distinctions is essential when comparing data across markets or historical periods.
Special | A | B | C | D | E | F | G | H | I | J | K | L | M | N | O | P | Q | R | S | T | U | V | W | X | Y | Z | ALL
C
Cash-and-Carry ArbitrageCash-and-carry arbitrage is a relative-value strategy that seeks to lock in a futures price above the cost of acquiring and carrying the corresponding cash asset. In the classic trade, the arbitrageur buys the underlying asset in the spot or cash market and simultaneously sells the related futures contract, then holds the asset until the futures position converges with cash or is settled, using delivery when the contract and the strategy call for it. The trade is therefore built around a financing-and-carry relationship, not a directional forecast. The futures premium is not the arbitrage profitThe relevant comparison is between the futures sale price and the all-in net cost of owning the cash asset to the futures horizon. For a storable physical commodity, that cost can include financing, storage, insurance, handling and delivery-related charges. For a financial asset, financing is also central, while income received during the holding period—such as dividends or coupons—reduces net carry. A futures price above the current spot price is therefore not enough by itself: contango can simply be the price relationship required to compensate the holder for carrying the asset. Suppose an asset can be bought for 100 and a futures contract sold for 104. If the financed cost of carrying and settling the asset to expiration is 5, the visible four-point cash-futures spread is not an arbitrage profit. If the modeled carrying and settlement cost is 2, both legs can be executed and maintained at those terms, and no material costs or mismatches have been omitted, the remaining two-point spread is the theoretical cash-and-carry margin before taxes. Deliverability can decide whether the arbitrage is realIn physically settled commodity markets, a generic spot quote may be a poor proxy for the asset that can actually satisfy futures delivery. Contract grade, delivery location, freight, quality differentials and tender-related costs can determine whether the purchased inventory is economically equivalent to the futures deliverable. This is why an apparent arbitrage on a screen can disappear when the path from cash inventory to acceptable delivery is modeled correctly. The same principle applies to bond futures with multiple eligible delivery securities: the deliverable chosen, its conversion mechanics and the settlement convention can materially alter the economics. Cash-and-carry activity also helps keep cash and futures prices aligned as settlement approaches. Buying cash while selling futures can increase demand in the cash market and add selling pressure in futures, narrowing an excessive discrepancy. But the textbook lock is only as strong as its implementation. Variable funding costs, margin liquidity needs, execution slippage, delivery constraints, mismatched assets or an inability to hold the trade through the relevant settlement process can leave residual risk. The practical boundary is simple: cash-and-carry arbitrage is not synonymous with a futures premium, contango or a wide cash-futures spread. It exists only when an executable cash-plus-carry position can be matched against the futures sale at a sufficiently favorable all-in price. | |
CointegrationCointegration is a statistical property of two or more nonstationary time series that share a stable long-run relationship. In the common case where each series is integrated of order one, I(1), the individual price levels may wander over time, but the series are cointegrated if a non-zero linear combination of them is stationary, I(0). If a vector of series is denoted by Xt, cointegration therefore requires a vector of coefficients β such that β′Xt is stationary even though the components of Xt are not stationary in levels. This distinction separates cointegration from correlation. Correlation measures co-movement over a specified sample or window; cointegration concerns whether nonstationary series share stochastic trends in such a way that a particular linear combination does not drift without bound. Two markets can therefore be highly correlated without being cointegrated, while cointegrated series need not maintain a consistently high short-horizon correlation. Cointegration is also more specific than simply observing that two prices sometimes converge after diverging. The stationary combination is the key objectFor two price series, the relevant relationship is generally not their raw difference. A relation such as yt − βxt may be stationary for an estimated coefficient β even when yt − xt is not. The cointegrating vector therefore determines the relative weighting that removes the shared nonstationary trend. In systems containing more than two I(1) variables, more than one independent stationary combination can exist; the number of such relationships is called the cointegration rank. Johansen's multivariate framework explicitly estimates and tests this rank rather than reducing the problem to a collection of pairwise relationships. Cointegration also has a dynamic implication. Under the conditions of the Engle–Granger representation theorem, cointegrated variables admit an error-correction representation: short-run changes can respond to the previous period's deviation from the long-run relation. This does not mean that every deviation must close quickly or that one particular variable must do the adjusting. The speed and location of adjustment are empirical properties of the system. A relationship can be statistical without being permanentA cointegration result is conditional on model specification and sample evidence. Deterministic terms, lag choices, sampling frequency and the assumed integration properties of the inputs can affect formal tests. More importantly, a historical stationary combination can cease to describe the data after a structural break in the relationship. Research on regime-shift cointegration shows that conventional tests that assume constant coefficients can lose substantial power when the long-run intercept or slope changes. For market research, this makes stability testing economically important: evidence that a spread was cointegrated over one period is not proof that the same hedge ratio represents a durable relationship in another regime. Cointegration is therefore most useful as evidence of a constrained long-run statistical relationship, not as a directional trading signal or a guarantee of mean reversion. Its practical value comes from identifying combinations of nonstationary variables that behave stationarily and then testing whether that relationship remains economically interpretable and statistically stable. | |
Commercial TraderA Commercial Trader is a reportable trader assigned to the commercial classification in the U.S. Commodity Futures Trading Commission’s Legacy Commitments of Traders (COT) framework. The classification is based on the trader’s predominant business purpose, as self-reported on CFTC Form 40 and reviewed by CFTC staff for reasonableness; commercial classification generally reflects use of the relevant market for commercial hedging or risk management. It is a trader-level classification, not a label assigned separately to each position. Commercial traders also appear in Supplemental COT reporting, but Commercial Trader is not a classification in the Disaggregated COT or Traders in Financial Futures (TFF) frameworks. Why “commercial” is broader than “producer hedger”The Legacy COT divides reportable open interest between Commercial and Non-Commercial classifications. For physical commodity markets covered by the Disaggregated COT, the CFTC uses four more granular categories: Producer/Merchant/Processor/User, Swap Dealer, Managed Money and Other Reportables. CFTC explanatory notes state that traders represented within the broad Legacy commercial category include both traditional physical-market participants—producers, merchants, processors and users—and swap dealers whose futures positions manage or offset swap-related risk. Those populations are reported separately in the Disaggregated framework. A Legacy Commercial total therefore is not interchangeable with Producer/Merchant/Processor/User and should not be read as a pure measure of physical producers’ hedging. Classification also does not reveal the purpose of every position. CFTC methodology classifies traders from reported business-purpose information and staff review, while the Commission states that it does not know the specific reasons for individual positions. A trader can have different classifications across commodities, and positions in a commodity enter the category assigned to that trader rather than being individually labeled as hedges or speculative trades. Consequently, a large net long or net short Commercial position does not by itself establish a unified directional view, nor does it constitute a stand-alone forecasting signal. A 1982 methodology breakHistorical comparisons require an additional distinction. From the origins of COT reporting through the pre-1982 regime, reported positions were classified by trading activity as hedging or speculative. In 1982, after changes to large-trader reporting, the COT framework began classifying positions by reference to the trading entity as commercial or non-commercial. Those concepts are related but not identical. A long-horizon series that treats pre-1982 “hedging” observations and later “Commercial” observations as one unchanged variable can therefore introduce a classification break into the research. Commercial positioning is best interpreted with the applicable report family, classification methodology and historical regime kept explicit. | |
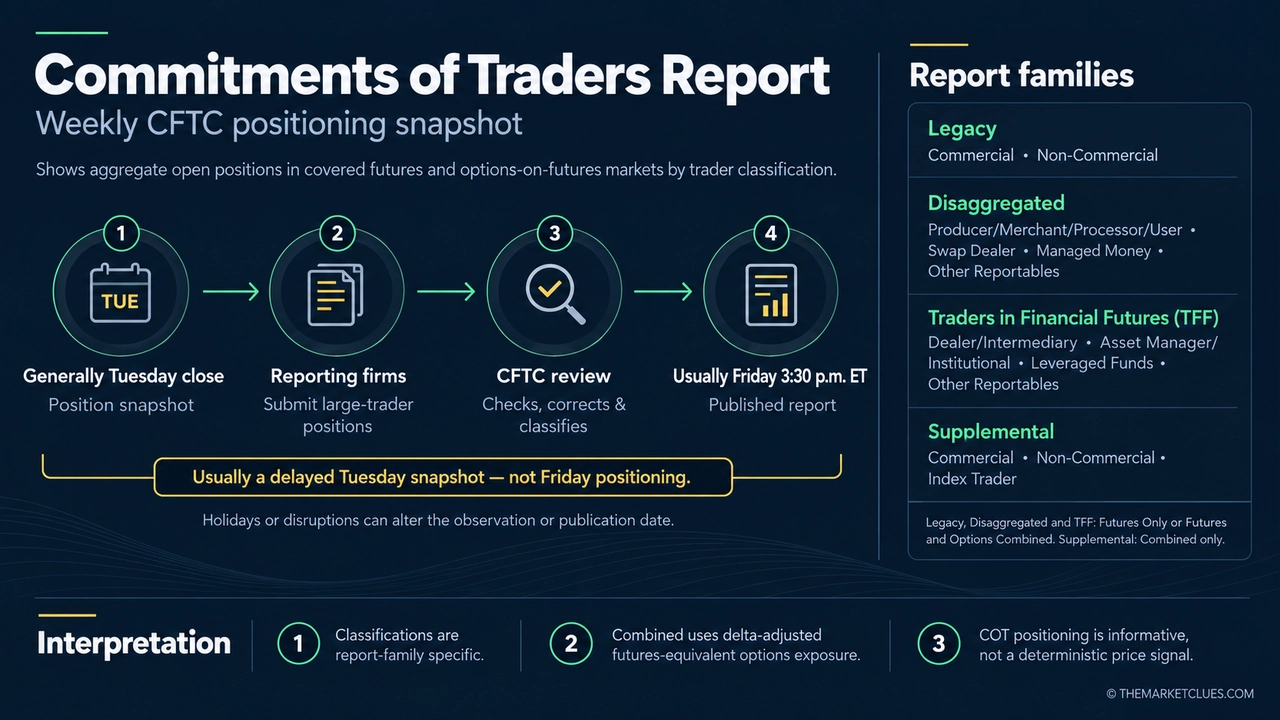
Commitments of Traders ReportThe Commitments of Traders Report (COT Report) is a set of weekly publications from the U.S. Commodity Futures Trading Commission (CFTC) that shows aggregate open positions in covered futures and options-on-futures markets by trader classification. It is a positioning snapshot, not a record of who traded during the week or why each position was opened. Its categories depend on the applicable report family, so similarly named or economically similar groups should not be treated as interchangeable across reports. COT data generally describe positions as of the close of business on Tuesday and are published at 3:30 p.m. Eastern Time on Friday. Holidays or other disruptions can alter the observation date, the publication date, or both. The CFTC receives large-trader position data from reporting firms and uses the intervening period to correct and verify them. A Friday release therefore does not show Friday positioning: it is normally a delayed Tuesday snapshot.
Which COT report are you reading?The Legacy report classifies reportable positions as Commercial or Non-Commercial. The Disaggregated report for physical commodity markets uses Producer/Merchant/Processor/User, Swap Dealer, Managed Money and Other Reportables. Traders in Financial Futures (TFF) uses Dealer/Intermediary, Asset Manager/Institutional, Leveraged Funds and Other Reportables for financial markets. The Supplemental report shows Commercial, Non-Commercial and Index Trader classifications for selected agricultural markets. Legacy, Disaggregated and TFF are available in Futures Only and Futures and Options Combined formats; the Supplemental report is combined only. Report family determines the classification framework, while report format determines whether options are included. Trader labels describe the CFTC classification framework, not the motive behind every contract. Classification is based primarily on the trader's reported predominant business purpose, subject to CFTC staff review. A trader classified as a Producer/Merchant/Processor/User, for example, can hold positions in that commodity that are not hedges. Category totals can therefore describe positioning structure without identifying each participant's intent. Reporting thresholds also require care. When a trader reaches the applicable large-trader reporting level in a single futures month or option expiration, reporting firms report that trader's entire position across all futures and option expirations in that commodity, not merely the amount above the threshold. A market generally appears in COT reporting only when at least 20 traders are reportable. Nonreportable Positions are derived as the residual between total open interest and Reportable Positions. Combined does not mean raw futures plus raw optionsIn the Futures and Options Combined format, option positions are converted to futures-equivalent exposure using delta factors before being combined with futures positions. Long calls and short puts contribute to long futures-equivalent exposure; short calls and long puts contribute to short futures-equivalent exposure. The combined report is therefore an exposure-adjusted view, not a simple count of option contracts added to futures contracts. Comparing Futures Only with Combined data also requires attention to spreading treatment, so simple subtraction should not automatically be interpreted as a clean options-only positioning series. COT data can reveal concentration, category-level positioning and changes through time, but those observations are not directional signals. Extreme net positioning can persist, classifications can change, and similar aggregate positions can arise from different motives. The report is most informative as a structured, lagged measure of market participation rather than a prediction of what price must do next. | |
Commodity CycleA commodity cycle is an irregular sequence of expansion and contraction in a commodity market, most visibly expressed through price booms and slumps and often accompanied by changes in inventories, production, demand and investment. The word cycle does not imply a fixed or reliably repeating timetable. Turning points emerge from shocks and delayed responses whose timing and importance differ across commodities. The delay is central to the mechanism. Strong demand or a supply disruption can tighten availability and raise prices faster than production capacity can respond. Higher prices may encourage additional output, investment, substitution or recycling, but mines, wells, processing capacity, acreage and other sources of supply can adjust on very different timescales. If new supply arrives after demand has cooled, the response that relieved scarcity can contribute to excess. Weak prices may then discourage investment or close high-cost capacity, reducing the buffer available against a later shock. Inventories can amplify or cushion this process, but an Inventory Cycle is not synonymous with the broader Commodity Cycle. Several clocks can run at onceA Commodity Cycle can overlap with the Business Cycle without being identical to it. Industrial commodities are often sensitive to global economic activity, while agricultural markets can be dominated by weather and commodity-specific supply shocks. Longer investment responses may also sit on top of shorter macroeconomic fluctuations. A World Bank decomposition distinguished conventional 2–8-year business-cycle movements from 8–20-year medium-term movements associated with investment and found that the medium-term component explained roughly twice as much commodity-price variability on average as the business-cycle component. The mix nevertheless differed substantially across commodity groups, so the result is not a universal timing rule. Cycle dating is method-dependentCommodity price cycles do not have a single standardized dating convention. Researchers can identify different turning points depending on the price series, sample, frequency, inflation adjustment, filtering technique and rules used to qualify a movement as a cycle. One World Bank study published in 2025, for example, imposed a minimum 12-month phase, a minimum 36-month full cycle and a 15% amplitude threshold before classifying suitable price movements as cycles. Those parameters are research choices, not laws of commodity markets. Seasonality is different again: it describes tendencies linked to recurring calendar effects, whereas Commodity Cycle phases can have irregular lengths. For research, the useful question is therefore not simply “where are we in the cycle?” but which mechanism is producing the observed phase and what evidence would show that it is changing. | |
ConsumptionConsumption is the quantity of a commodity that is used or absorbed within a defined market, geography and period. In physical-market analysis it is a realized or estimated flow, not the same thing as demand: demand describes the quantity buyers would take under particular prices and conditions, whereas consumption records or estimates the quantity used under the conditions that prevailed. What the number is actually measuringConsumption can be observed directly for some uses, but many commodity datasets infer part or all of it from a supply-and-disposition balance. A simplified identity is beginning stocks plus production plus imports equals domestic use or consumption plus exports plus ending stocks, with commodity-specific adjustments for processing, losses, transfers or statistical residuals. Rearranging the balance means consumption may be the amount needed to reconcile the other components. Labels such as “apparent consumption,” “disappearance” and “domestic use” therefore cannot automatically be treated as direct measures of final end-user purchases. Official datasets make this distinction concrete. The U.S. Energy Information Administration uses petroleum product supplied as a proxy for consumption because it measures product leaving the primary supply chain rather than directly surveying final consumption. U.S. Geological Survey mineral statistics calculate apparent consumption from production, trade and stock changes for many commodities. That scope can matter as much as the arithmetic: raw-material apparent consumption may exclude a mineral contained in imported or exported manufactured goods, so it can understate or overstate broader U.S. use when downstream trade is important. USDA food-availability estimates likewise use supply-and-use balances in which availability is calculated as a residual after measurable uses are deducted. Consumption is not a pure demand signalA rise or fall in consumption does not by itself reveal why use changed. Prices, substitution, weather, operating rates, policy, supply constraints and logistics can all affect realized consumption. A shortage can reduce consumption even when willingness to buy remains strong; ample supply and low prices can raise use without establishing a lasting increase in underlying demand. For research, the critical checks are scope and construction: which uses are included, whether the figure is directly measured or residual, the units and period, and how stocks, trade and processing are handled. A residual consumption estimate can change when inventories, imports, exports or other balance-sheet components are revised even if no new evidence about final users appears. Consumption is therefore central to physical market balances, but it can mislead when treated as a stand-alone measure of demand strength. | |
ContangoContango is a futures term structure in which progressively deferred contract months trade at higher prices than nearer-dated months, producing an upward-sloping curve. It is the opposite of backwardation. In looser market usage, a particular futures contract may also be described as being in contango when it trades above the contemporaneous spot or cash price of the underlying asset. That spot-versus-futures comparison describes one maturity relative to the cash market; it does not by itself establish the shape of the full futures curve. In either usage, contango describes relative prices observed now across different delivery dates, not a forecast that the future spot price must rise. Carry, inventory and the shape of the curveIn storable, physically deliverable commodities, contango often reflects the economics of carrying inventory through time. Financing, storage, insurance and other carrying costs tend to raise the price required for later delivery, while the economic benefit of having physical inventory available — convenience yield — works in the opposite direction. Ample inventory or weak near-term scarcity can therefore be consistent with contango, but the curve is not determined by storage costs alone: expectations, financing conditions, logistical constraints and deliverability can also affect calendar spreads. A practically important distinction is that visible contango does not automatically create a profitable storage trade. A cash-and-carry opportunity requires the deferred premium to exceed the relevant financing, storage, insurance, transaction and delivery-related costs, and the asset must actually be storable and deliverable on the required terms. When those conditions are met, the curve can reward carrying inventory forward; when storage capacity is scarce or operational constraints bind, the same quoted spread may be insufficient. What contango means for a futures positionFor a trader maintaining long futures exposure by rolling through successive contracts, contango is commonly associated with negative roll yield. The economic effect comes from holding contracts whose prices may decline relative to the cash market as they approach expiration, not from the roll transaction being a guaranteed standalone loss. Realized futures returns depend on how spot prices and the entire curve move while the position is held, so price appreciation can offset negative roll effects and the curve can change or invert. Convergence of a particular futures contract toward its relevant cash or settlement reference also does not require the entire futures curve to flatten. The mechanism differs across markets. In equity-index futures, for example, theoretical futures value reflects the cash index, financing costs and expected dividends rather than physical storage. Contango is therefore a term-structure condition, not a universal signal of oversupply, bearishness or future price direction. | |
Contract MonthA contract month is the month-and-year designation of a particular futures contract series. For physically delivered futures, it identifies the month and year in which delivery occurs under the applicable exchange rules; for cash-settled futures, it identifies the month and year in which final settlement occurs. It is commonly synonymous with delivery month. The label identifies a listed maturity, but it does not by itself tell you the contract's last trading day, first notice day, expiration date or exact delivery or settlement date. A month label, not a single dateThose lifecycle dates are established separately by the rules of the particular contract. Exchanges may list consecutive calendar months, selected quarterly or seasonal maturities, or another product-specific sequence. Each listed contract month is a distinct futures series with its own price, open interest and lifecycle. NYMEX WTI crude oil shows why the distinction matters. Trading in the expiring contract terminates according to a schedule tied to the twenty-fifth calendar day of the month preceding the delivery month, subject to the rule's business-day and holiday provisions. Physical delivery, by contrast, takes place no earlier than the first calendar day and no later than the last calendar day of the delivery month. A December WTI contract therefore stops regular trading in November even though December is its delivery month. Contract identity versus position on the curveContract Month also differs from Front Month and Deferred Contract. Contract month identifies a specific maturity, such as December 2026. Front month and deferred describe where a listed maturity sits relative to other currently traded maturities. As nearer contracts expire, the same contract month can move from deferred status toward the front of the futures curve without changing its underlying month-year identity. This distinction matters in market data, calendar spreads, contract rolls and continuous-futures research. A contract-month label should therefore be treated as the identity of the futures series, while its exact trading, notice, delivery and settlement dates should be taken from the applicable contract specifications and exchange rules. | |
Contract RollContract roll is the process of closing or offsetting a futures position in one contract month and establishing a replacement position in a later contract month to maintain substantially similar market exposure. The expiring contract is not extended: one maturity is exited and another is entered, usually before expiry, settlement or—where relevant—notice and delivery procedures become operationally important. Changing maturity without leaving the marketA trader who is long the expiring contract typically sells it and buys a deferred contract; a short trader buys back the expiring contract and sells the deferred contract. The legs can be executed separately, but exchange-listed calendar spreads often allow the closing and opening legs to be traded together. That reduces the time gap between them and therefore the risk of slippage from an intervening market move. A calendar spread is not automatically a contract roll, however: the same structure can also be held as a relative-value position between maturities. The replacement contract normally trades at a different price because it sits at a different point on the futures term structure. That price difference is part of the roll transaction, but contract roll should not be treated as a synonym for roll yield. Contract roll describes the transfer of exposure from one maturity to another; roll yield is a return concept associated with maintaining futures exposure through successive contracts and with how those contracts behave as time passes. Roll date is not the same as deadlineThere is no universal roll date. Timing depends on contract rules, liquidity, delivery or settlement mechanics and the trader's objective. Liquidity can migrate to the next contract before the nearby contract stops trading. CME Group's equity-index documentation, for example, publishes customary roll dates while stating that participants may roll from one quarterly month to the next at any time they choose. The practical lesson is that a quoted “roll date” may describe a liquidity convention rather than a mandatory exit date. Rolling the same number of contracts also does not always preserve the same risk exposure. CME Group's Treasury-futures documentation notes that nearby and deferred contracts can have different DV01, so a fixed 1:1 roll can change portfolio duration even though the contract count is unchanged. The same implementation issue appears in research: a continuous futures series must define when it switches contracts and which contract replaces the old one. Fixed-date, days-to-expiry and liquidity-based roll rules can therefore produce different historical series, affecting charts, indicators and backtests. | |